Tax filing decisions can become harder when a return depends on probate documents, a trust, or decisions made for an older family member. Schoffstall Elder Law is listed as a Probate & Estate Attorney, and its official website describes work in estate planning, probate, estate and trust administration, special needs planning, healthcare financing, and guardianships. That published scope does not by itself establish that the firm prepares every type of tax return. It does, however, give families a useful starting point for sorting the estate records before they speak with a tax professional or assign responsibility for an IRS filing.
Estate records should be organized before the return is discussed
An estate-related tax question may involve more than a folder of receipts. A family may need to identify the date of death, the person authorized to act, the current status of probate, trust documents, prior returns, account statements, and notices already received. The right records depend on the matter and tax year, so a preparer should confirm what is actually needed rather than relying on a generic checklist. Schoffstall’s public practice-area descriptions make probate, estate administration, and trust administration relevant subjects for that initial records conversation.
The practical goal is not to predict a deduction or promise a filing result. It is to establish who controls the records, which documents are final, and whether an estate or trust has obligations separate from an individual return. Those distinctions can affect the questions sent to a CPA, enrolled agent, or other tax professional.
Schoffstall’s published scope points to a coordination question
The official website says the firm helps with estate plans and with administering an estate through probate. It also describes planning for people with special needs and powers of attorney and elder-law planning in the local listing information. These signals suggest that a family may want to clarify the document and authority side of a tax matter before asking for filing help. They do not prove that the firm offers tax preparation, prepares a particular return, or handles an IRS dispute.
That distinction matters when a family is comparing providers. A lawyer handling probate or trust administration may help explain the legal status of documents, while a tax preparer may handle the return itself. Sometimes the same professional team coordinates both roles; sometimes the client must assemble the team. The first call should establish the boundary in writing.
Orefield contact details make the first call more precise
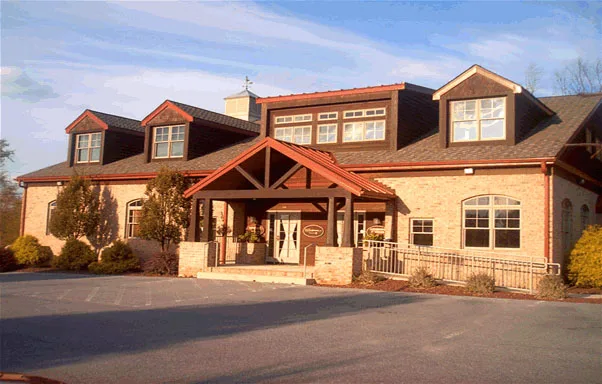
Schoffstall Elder Law’s official website lists 2987 Corporate Court, Suite 200, Orefield, PA 18069, and the business phone as 610-706-0686. The site describes the office as west of Allentown, north of Route 78 on Route 100. Families should confirm the current address, appointment process, jurisdiction, and document-submission method directly before traveling or sending sensitive records. The business website is http://www.lvelderlawattorney.com/.
Those details are useful because a focused call is more productive than asking broadly for “tax help.” The caller can explain whether the issue concerns a decedent’s records, an active trust, a guardianship, a power of attorney, or a family member’s planning documents. The office can then state whether the request fits its current practice and whether a separate tax professional should be included.
Four questions can separate document work from tax preparation
First, which professional should determine the filing requirement for the individual, estate, or trust, and which professional will prepare the return? Second, what authority documents should accompany the records, such as letters connected with probate, a trust instrument, or a power of attorney? Third, which tax years and notices are within the requested scope, and who will communicate with the IRS if a question arises? Fourth, will the client receive a written list of missing records, deadlines to confirm, and the next responsible party?
Families should also ask how fees are explained, whether the matter is limited to estate planning or administration, and whether the office will coordinate with the tax preparer. Answers may change after the documents are reviewed. Keeping those answers separate from assumptions about a deduction, refund, or filing deadline helps prevent an avoidable handoff.
A careful handoff protects the quality of the filing record
Before sending documents, a family can create a dated inventory and retain copies of everything provided. Sensitive financial information should be transmitted through a method the receiving professional confirms. If the estate, trust, or individual return raises a technical IRS issue, the person preparing the return should identify the applicable question and explain what additional evidence is required. Schoffstall Elder Law may be a relevant contact for the estate-document side of that process, but the firm’s current tax-preparation role must be verified directly.
The strongest next step is therefore a defined conversation: describe the estate or planning status, identify the tax year, list the records available, and ask who owns each part of the work. That approach gives a family a clearer basis for choosing professional help without treating a probate-and-estate listing as an unsupported promise about tax filing services.